Silicon Valley Bank Shut Down by Regulators, FDIC Takes Control in Largest U.S. Bank Failure Since 2008
SANTA CLARA, Calif., March 10 - Silicon Valley Bank was closed by California regulators on Friday and placed under the control of the Federal Deposit Insurance Corp., the largest U.S.

By Priya Kanth, Business & Economy
· 2 min read
The essentials
- •The California Department of Financial Protection and Innovation shut the bank and named the FDIC as receiver.
- •The FDIC said it created a new institution, the Deposit Insurance National Bank of Santa Clara, to hold all insured deposits.
- •Customers with money above the $250,000 insurance limit will not get all of it back right away.
- •Treasury Secretary Janet Yellen met with banking regulators on Friday and expressed "full confidence" in their ability to respond, Reuters reported.
The short answer
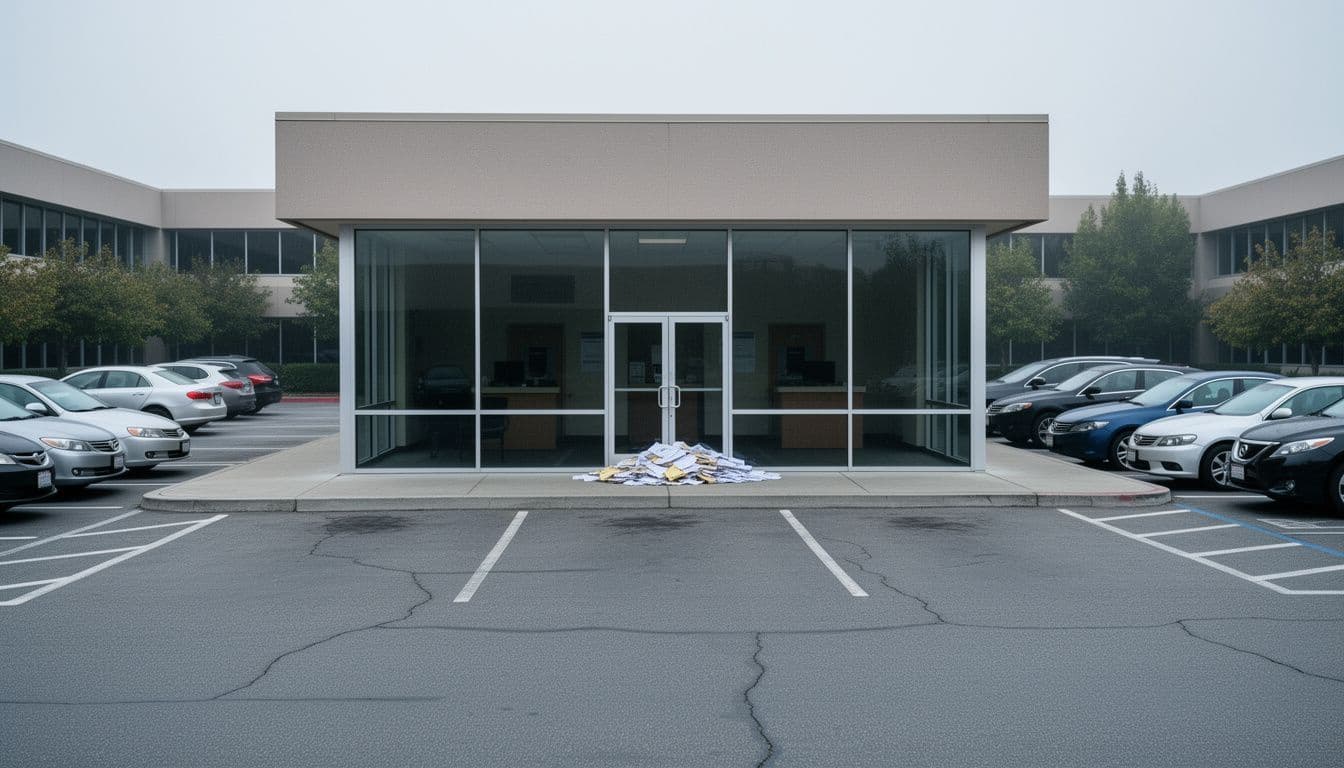
SANTA CLARA, Calif., March 10 - Silicon Valley Bank was closed by California regulators on Friday and placed under the control of the Federal Deposit Insurance Corp., the largest U.S. bank failure since the 2008 financial crisis. The California Department of Financial Protection and Innovation shut the bank and named the FDIC as receiver. The bank had about $209 billion in assets and about $175.4 billion in deposits at the end of 2022, the FDIC said.
SANTA CLARA, Calif., March 10 - Silicon Valley Bank was closed by California regulators on Friday and placed under the control of the Federal Deposit Insurance Corp., the largest U.S. bank failure since the 2008 financial crisis.
The California Department of Financial Protection and Innovation shut the bank and named the FDIC as receiver. The bank had about $209 billion in assets and about $175.4 billion in deposits at the end of 2022, the FDIC said. It was the 16th largest bank in the country, and only Washington Mutual, which failed in 2008, was a bigger U.S. bank failure.
The FDIC said it created a new institution, the Deposit Insurance National Bank of Santa Clara, to hold all insured deposits. Insured depositors will have full access to their money no later than Monday morning. The bank's 17 branches in California and Massachusetts are due to reopen Monday during normal business hours.
Customers with money above the $250,000 insurance limit will not get all of it back right away. The FDIC said uninsured depositors will receive an advance dividend within about a week, plus a receivership certificate for the rest. At the end of last year, about 89% of the bank's deposits were uninsured, Reuters reported.
The collapse came fast. SVB said this week that it had sold a $21 billion bond portfolio at a loss of $1.8 billion and planned to raise $2.25 billion by selling stock. Customers, many of them startups and venture-backed companies, began pulling money out. The share sale could not be completed as the stock fell, losing more than 60% of its value. Trading in the shares never opened on Friday.
Treasury Secretary Janet Yellen met with banking regulators on Friday and expressed "full confidence" in their ability to respond, Reuters reported.
Why it matters: SVB was the main bank for a large share of the U.S. startup economy, and many of those companies keep their operating cash there. A company that cannot reach its cash cannot make payroll. Rising interest rates cut the value of the bonds the bank held. Investors are now asking whether other banks hold similar losses on their bond portfolios. U.S. bank stocks lost more than $100 billion in value over the past two days.
Borrowers have been told to keep making their loan payments as usual.
The first test comes Monday morning, when the branches reopen and the market finds out how many customers show up.
Sources
- 01State Regulator Closes Silicon Valley Bank and Appoints FDIC Receiver, FDICfdic.gov
- 02US closes Silicon Valley Bank in biggest collapse since 2008, AFP via Tech Xploretechxplore.com
- 03SVB is largest bank failure since 2008 financial crisis, Reuters via Kitcokitco.com
- 04Collapse of Silicon Valley Bank, Wikipediaen.wikipedia.org
Corrections
No corrections have been made to this article.
About the reporter
Senior Business & Economy Reporter, Trestlewire
I was an equity research analyst for five years and have been a financial reporter since 2000. I covered the end of the dot-com bubble from a markets desk, spent the autumn of 2008 reading bank filings at two in the morning in Chicago, and have written about every Federal Reserve rate cycle since. The lesson from all of it is short: the number comes first, and the story is the explanation for the number.
Read full bio and all stories →The Morning Wire
The day’s reporting, in your inbox before nine.
Free. Unsubscribe any time. We never share your address.