Fed's Debit Fee Cap Is 21 Cents. Its Own Data Put Processing Cost at 4.1. An Appeals Court Just Struck the Rule Down
The Eighth Circuit ruled the Fed let fixed costs into Regulation II's flat cap and ordered a rewrite. Covered banks collected an average of 23 cents a swipe in 2023.

By Priya Kanth, Business & Economy
· 5 min read
What to know
- •On October 26, 2026 the Eighth Circuit affirmed a ruling vacating the Fed's Regulation II debit swipe fee cap of 21 cents plus 0.05 percent, and sent it back for a rewrite.
- •The Fed's 2023 survey found covered banks averaged 4.1 cents in authorization, clearing and settlement costs per transaction, against an average covered fee of 23 cents.
- •The cap exceeded average costs, fraud losses included, for 80.1 percent of covered issuers, which handled 99.2 percent of covered transactions.
- •TD Cowen's Jaret Seiberg forecasts a compliant cap under five cents for the largest banks; that is an analyst estimate, not a Fed proposal.
- •Bank groups are expected to seek Supreme Court review, and a separate Sixth Circuit case, Linney's Pizza, could produce a conflicting ruling.
The Federal Reserve's debit card fee cap lets large banks charge merchants 21 cents plus 0.05 percent of the sale on every swipe. The Fed's own 2023 data put the average cost of authorizing, clearing and settling a covered transaction at 4.1 cents. On Monday, October 26, the Eighth Circuit Court of Appeals ruled that the gap between those two numbers is not a rounding error but a legal defect, and ordered the Fed to rewrite the rule.
What this means for you
The appeals court affirmed a 2025 district court ruling that vacated Regulation II, the rule that sets the maximum debit swipe fee at banks with $10 billion or more in assets. The Fed must now rebuild the cap around the incremental cost of each transaction. A lower cap would cut what stores pay on debit sales. Whether shoppers see lower prices, or banks recoup the money through checking account fees, is unsettled.
What the court said the Fed got wrong
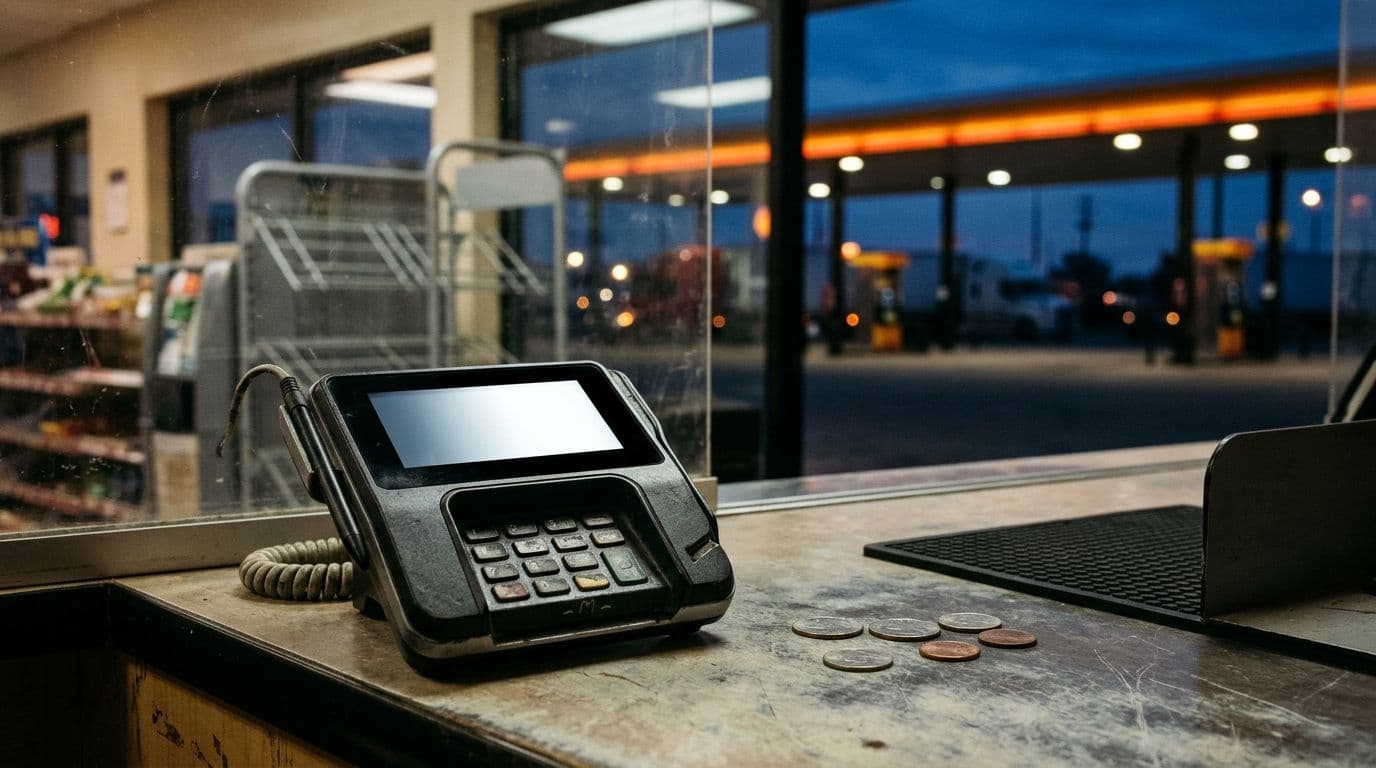
Corner Post, a North Dakota truck stop, sued the Fed in 2021. The case turned on a Dodd-Frank provision known as the Durbin Amendment, which says debit interchange fees must be reasonable and proportional to the issuer's costs. According to American Banker, Judge David Straus wrote for the court that the Fed broke the law by folding fixed costs into the cap. Those included network processing fees, fraud monitoring and fraud losses, none of which rise or fall with a single transaction. The statute, he wrote, points to the incremental costs of each one.
“The clearest sign of regulatory drift was the flat 21-cent cap because it applied to every transaction, no matter its cost.”
The remedy is narrower than the headline. America's Credit Unions reports the court vacated the rule and sent it back, saying the Fed must at a minimum sort its costs into those tied to a specific transaction and those that are not. That is a sorting job, not a ban on a cap.
4.1 cents
Average per-transaction authorization, clearing and settlement cost, covered issuers, 2023
Federal Reserve Regulation II survey. Excludes fraud losses. The average covered fee was 23 cents.
Here's what the spreadsheet says
The Fed's survey of 2023 data counts 100.7 billion debit and general-use prepaid transactions worth $4.66 trillion, with $34.12 billion paid in interchange. Of those, 61.67 billion were covered by the cap, at an average fee of 23 cents. Exempt transactions, from smaller banks, averaged 52 cents. The base cap exceeded average per-transaction costs, fraud losses included, for 80.1 percent of covered issuers, which handled 99.2 percent of covered transactions.
Multiply 61.67 billion by 23 cents and covered fees come to roughly $14.2 billion a year. That is my arithmetic from the Fed's averages, not a figure the Fed published. At 5 cents, the same volume would produce about $3.1 billion.
TD Cowen managing director Jaret Seiberg wrote in a Monday note that a compliant cap could be under five cents per transaction for the largest banks. That is an analyst's forecast, not a court finding or a Fed proposal. The Fed's last attempt, a 2023 proposal, would have cut the cap to 14.4 cents plus 0.04 percent and a 1.3-cent fraud adjustment. On a $50 purchase that is 17.7 cents instead of 24.5, a drop of nearly 28 percent, according to American Banker.
The banks' side
Ann Petros, vice president of policy engagement and credit union operations at America's Credit Unions, called the decision deeply disappointing. She argued that vacating the framework ignores the real operational and fraud prevention costs of running a debit network, and that a recalculated rule could prove administratively unworkable. A joint statement from six financial trade groups, including the American Bankers Association, said government price controls have harmed consumers from the start.
The cost data cuts both ways. The 4.1-cent figure leaves out fraud losses, which are exactly the cost banks say the cap must cover. The Fed's own comparison that includes them still found the cap above average costs for four in five issuers. The surveys do not show whether the cap covers costs at the one issuer in five where it does not.
Leslie Sarasin, president and CEO of the food industry association FMI, called the ruling a victory for grocery customers. Doug Kantor of the Merchants Payments Coalition, who is also general counsel for the National Association of Convenience Stores, said the Fed should promptly replace the rule and that two courts have now agreed banks collect billions more than the law allows.
What is still open
Brian Gardner, chief Washington policy strategist at Stiefel, expects bank groups to petition the Supreme Court within weeks, according to American Banker. The outlet reported it was unclear whether the Fed would appeal or start a rewrite. The sources reviewed for this story did not say when the ruling takes effect, and I found no Fed statement. America's Credit Unions also notes a separate challenge, Linney's Pizza, was argued before the Sixth Circuit the week before. There, the district court upheld the rule. Opposite rulings from two circuits would raise the odds of a Supreme Court hearing.
This account rests on trade-press and association reports of the opinion, not on the opinion itself, which I did not obtain. The Fed's 2023 survey is the primary source for the cost and volume figures. The number to watch is the replacement cap. If it lands near five cents, the money moving between banks and merchants shrinks by billions of dollars a year.
- Regulation II
- debit interchange
- Durbin Amendment
- Corner Post
- Federal Reserve
- swipe fees
Sources
- 01Regulation II (Debit Card Interchange Fees and Routing): 2023 data, Federal Reserve Boardfederalreserve.gov
- 02Appeals court confirms Fed set interchange fee too high, American Bankeramericanbanker.com
- 03Court rules Fed must re-write debit interchange fee cap, America's Credit Unionsamericascreditunions.org
- 04FMI welcomes ruling striking down debit swipe fee cap, Mass Market Retailersmassmarketretailers.com
Corrections
No corrections have been made to this article.
About the reporter
Senior Business & Economy Reporter, Trestlewire
I was an equity research analyst for five years and have been a financial reporter since 2000. I covered the end of the dot-com bubble from a markets desk, spent the autumn of 2008 reading bank filings at two in the morning in Chicago, and have written about every Federal Reserve rate cycle since. The lesson from all of it is short: the number comes first, and the story is the explanation for the number.
Read full bio and all stories →The Morning Wire
The day’s reporting, in your inbox before nine.
Free. Unsubscribe any time. We never share your address.